Japan PM Takaichi Rejects Blame for Weak Yen, High Rates
Prime Minister Sanae Takaichi has denied her administration's fiscal plans are causing market unease, as Bank of Japan Governor Kazuo Ueda warned of potential rises in long-term bond yields.
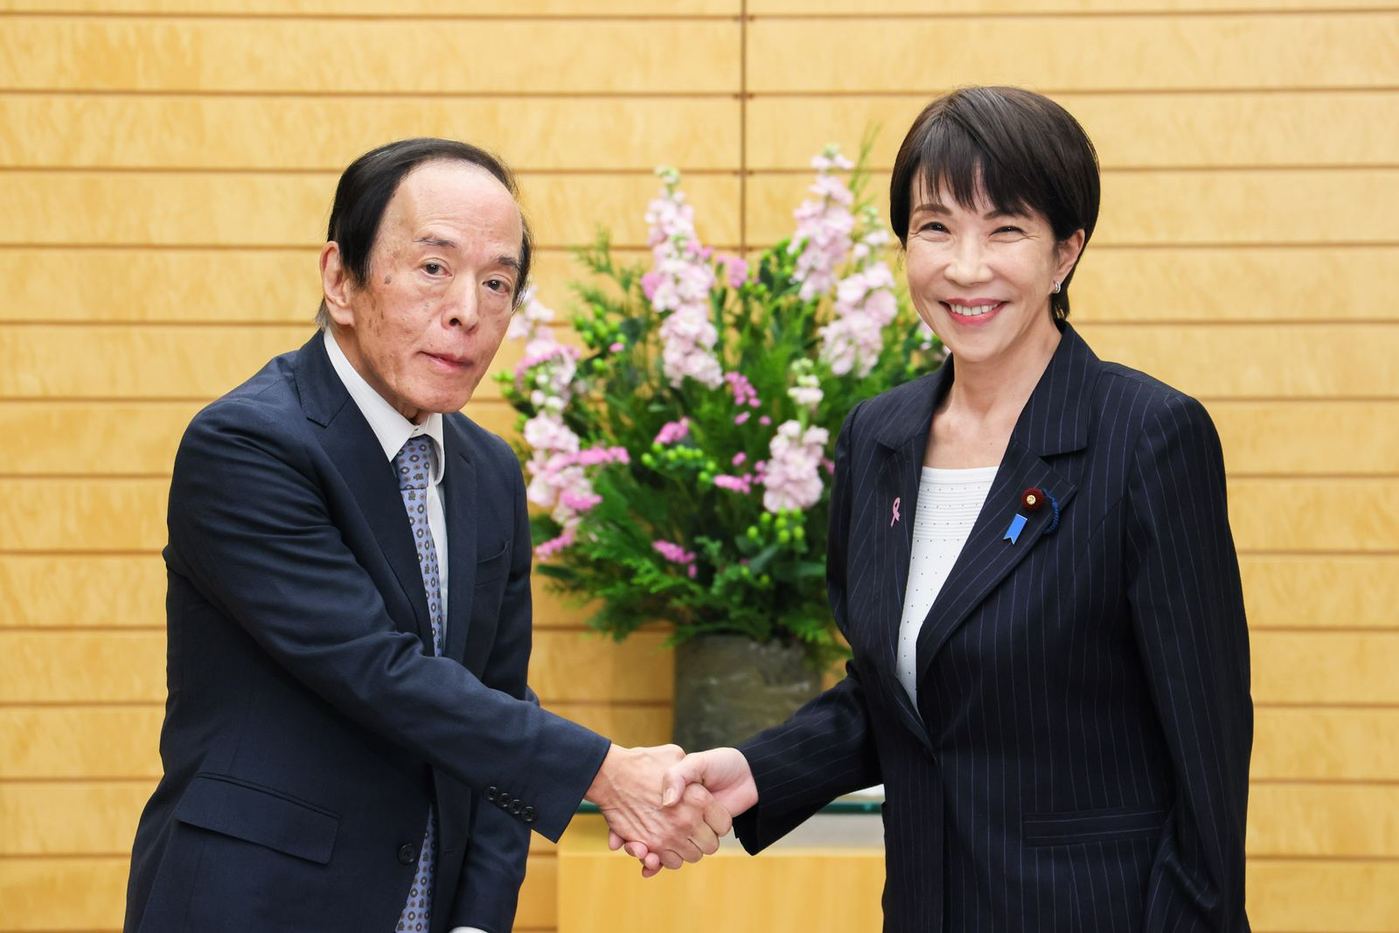
Takaichi Rejects Market Claims
Japanese Prime Minister Sanae Takaichi firmly dismissed claims in Parliament on 19 October that her policies are responsible for a weak yen and elevated interest rates. Ms Takaichi stated her government aims to foster a robust economy and ensure fiscal sustainability.
She also pledged to manage the issuance of Japanese government bonds (JGBs) appropriately within the upcoming fiscal year's budget, seeking to alleviate persistent market concerns regarding the nation's financial management.
Fiscal Policy Under Scrutiny
Markets have remained uneasy about Japan's significant debt and future spending initiatives. Earlier in 2026, initial drafts of an annual economic policy blueprint sparked concerns that the government was leaning towards a more expansionary fiscal stance. This perception contributed to a weaker yen against the US dollar and pushed long-term sovereign debt yields higher.
Growth Strategy Minister Minoru Kiuchi commented in September that Japan no longer requires an aggressive monetary easing or fiscal spending approach for reflationary policy. Finance Minister Satsuki Katayama has also clarified that Ms Takaichi is not a reflationist.
Bank of Japan's Inflation Outlook
Bank of Japan (BOJ) Governor Kazuo Ueda, who also appeared in Parliament, noted that underlying inflation is nearing the central bank's 2% target. Mr Ueda cautioned that long-term bond yields could increase if markets perceive the BOJ is not adjusting its benchmark policy interest rate at a suitable pace.
These comments highlight the delicate balance between the government's fiscal ambitions and the central bank's monetary policy objectives.
What Investors Are Watching
Investors are closely monitoring how the Japanese government plans to fund a proposed sales tax reduction on food and increased defence spending. The key concern is managing these expenditures without exacerbating the nation's already substantial debt burden.
The interaction between Ms Takaichi's fiscal management and the BOJ's rate decisions will shape the yen's trajectory and JGB yields in the coming quarters, impacting capital flows into Japanese assets.
This article is journalism, not investment advice; consult a licensed professional before making financial decisions. Market data is indicative, may be delayed, and should be verified with your broker or exchange before use.
Comments.
Comments are moderated. We remove what is unlawful, abusive or off-topic, and and you remain responsible for what you post.
Reader comments open soon. Until then, corrections and responses go to our newsroom, and we publish what we get wrong on Corrections.